Searching EarnIn vs Grant (or Grant vs EarnIn) usually means you need cash now and you want a straight answer: which app costs less, which pays more, and which one is less likely to waste your time. This comparison is written from ongoing personal use of cash advance apps — not a press-release rewrite.
If I could install only one of these two tomorrow, I would choose EarnIn. That is not a brand endorsement — it is the score from living with both fee models and amount patterns month after month.
Both apps are evaluated on the same rules I use site-wide: instant transfer preferred over 1–2 day deposits, fee pain measured by what actually leaves my pocket, and advance size judged by whether it helps a real bill — not by a marketing maximum I never received.
EarnIn vs Grant: quick comparison table
Start here. Green cells mark the better side of that row in my experience; red marks the weaker side. Then read the sections below for context, because a “win” on amount does not help if the fee destroys the value.
| Metric | EarnIn | Grant | Edge |
|---|---|---|---|
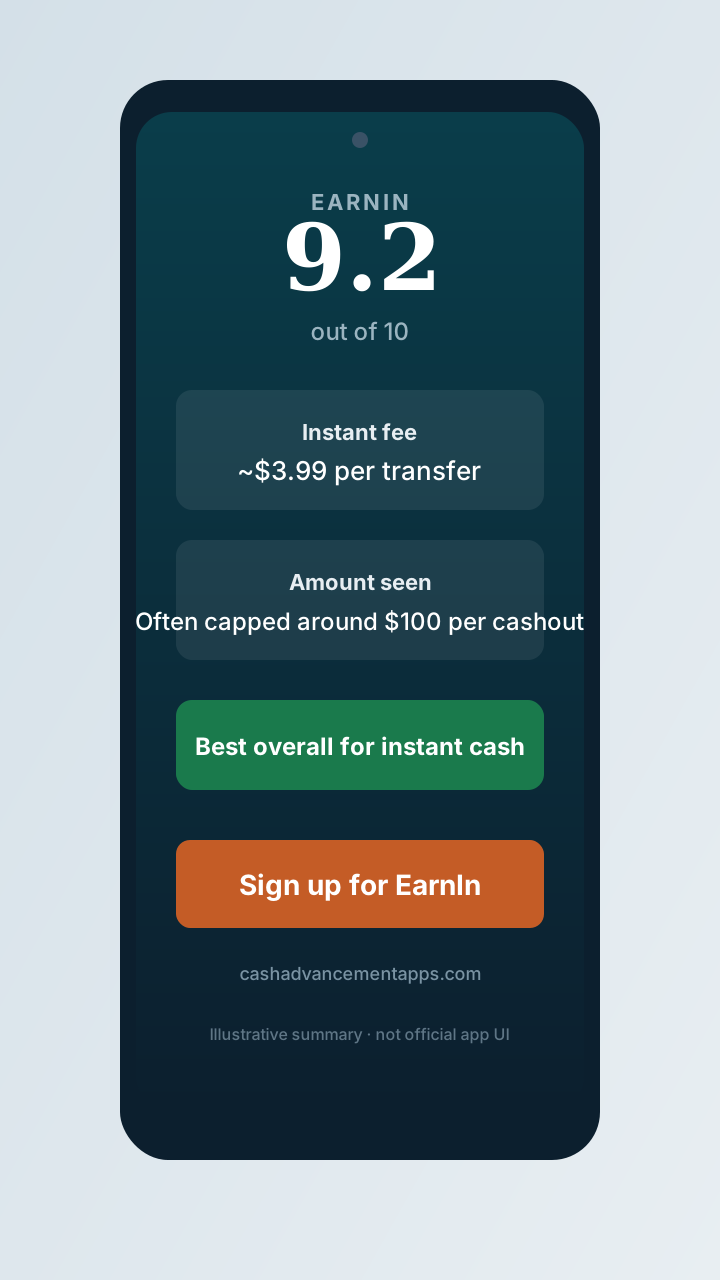
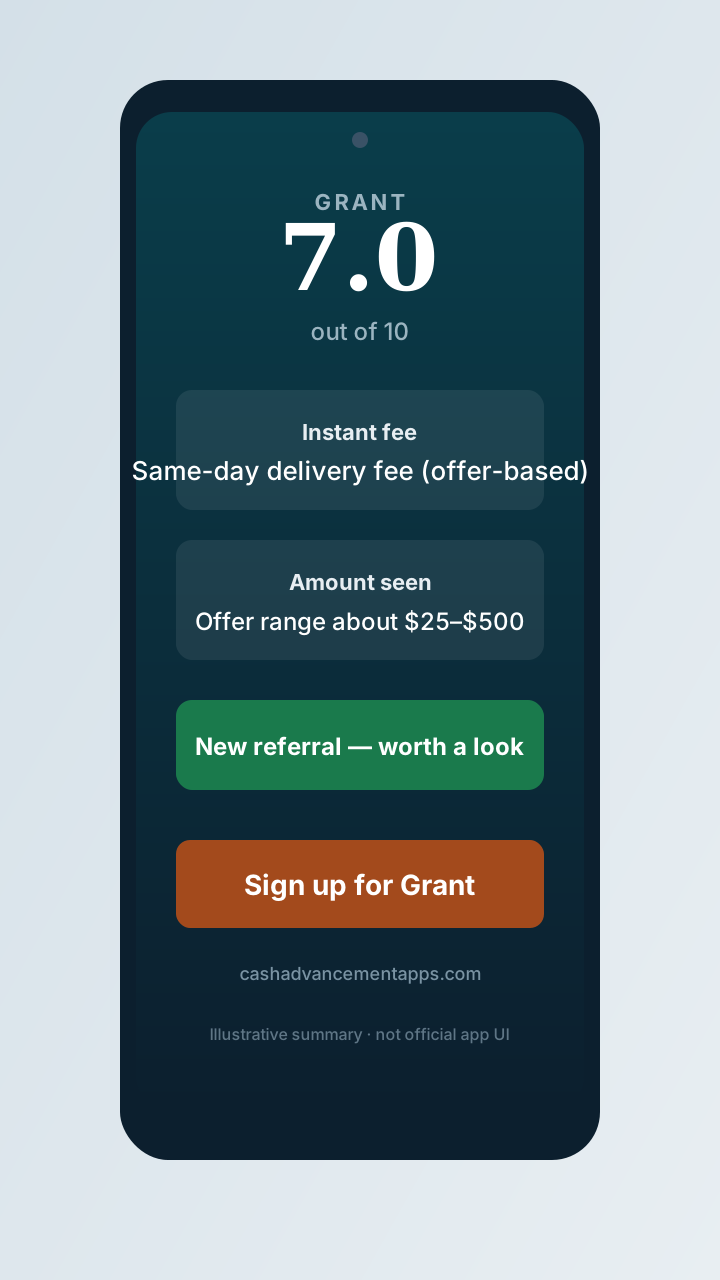
| Overall score | 9.2 / 10 | 7.0 / 10 | EarnIn |
| Instant fee | ~$3.99 per transfer | Same-day delivery fee (offer-based) | EarnIn |
| Amount experience | Often capped around $100 per cashout | Offer range about $25–$500 | Grant |
| Monthly / sub | Low / tip-style (no harsh upfront sub in my use) | Not a pay-first subscription in the invite | Context-dependent |
| Instant transfer | Yes | Same day for a fee (per offer) | See notes |
| Referral / bonus | Both get $35 | Bonus when you join via my invite | — |
| Best for | Cheapest usable instant pull when ~$100 is enough | People who want a bonus on signup and a wide stated range | — |
| Watch out | Per-cashout cap forces stacking for bigger gaps | Confirm the live fee before you cash out — offer copy is not the same as a settled personal ledger | — |
| Full reviews | EarnIn review | Grant review | — |
What each app is trying to be
EarnIn: Lowest fee I regularly pay for instant cash; capped near $100. Best for: Cheapest usable instant pull when ~$100 is enough. Watch out: Per-cashout cap forces stacking for bigger gaps.
Grant: Grant is on my referral list: invite bonus for you, stated advances about $25 to $500, no credit check in the offer, same-day delivery for a fee. Best for: People who want a bonus on signup and a wide stated range. Watch out: Confirm the live fee before you cash out — offer copy is not the same as a settled personal ledger.
That framing matters. Plenty of “vs” articles pretend every cash advance app competes for the same user. In reality, someone who needs a cheap $80 bridge is not shopping the same way as someone who needs ~$300 and will tolerate a monthly subscription.
Fees and monthly cost: the honest math
EarnIn wins the fee comparison in my notes.
EarnIn fee pattern
In my ongoing use the instant transfer fee lands around $3.99.
That is dramatically cheaper than Dave's near-$50 cashout pain and usually cheaper than MoneyLion's ~$8.99 per $100.
There is no 'pay the monthly fee before you even see an estimate' trap like Gerald or Vola.
Monthly / subscription notes for EarnIn: Low / tip-style (no harsh upfront sub in my use). Always price the subscription into the advance if one exists — a “free” cashout that requires a $19.99 gate is not free.
Grant fee pattern
Same-day cash is not free — the offer says delivery is available for a fee.
There is a signup bonus via my link; that does not erase the transfer fee.
Compare the live fee to EarnIn (~$3.99) before you pick Grant for a small advance.
Monthly / subscription notes for Grant: Not a pay-first subscription in the invite. Always price the subscription into the advance if one exists — a “free” cashout that requires a $19.99 gate is not free.
When I compare EarnIn and Grant side by side, I convert everything into cost to get usable dollars into my real bank account today. That is why Albert-style internal hops and Dave-style split cashouts get punished even when the headline advance looks okay.
Advance amounts and what I actually received
Grant has been stronger on usable advance size in my experience.
With EarnIn, my amount experience is: Often capped around $100 per cashout. With Grant, it is: Offer range about $25–$500. Your underwriting will differ because these products read deposit history, but repeated patterns still tell you which product tends to be stingy, generous, or capped.
EarnIn amount notes
I open EarnIn first almost every month when I need cash today.
The fee is what I love most — about $3.99 a transfer instead of Dave-level pain.
They are relatively generous for that price, but the practical cap sits near $100 each pull.
Grant amount notes
I added Grant because I use it for cash advances and the invite pays a bonus when someone joins through my link.
The public offer is about $25 to $500, no credit check, no late fees, and same-day delivery for a fee.
Treat the top of that range as a ceiling you may not get — underwriting still depends on your account.
Speed: instant cash vs friction
EarnIn instant transfer status in my use: Yes. Grant: Same day for a fee (per offer).
If an app takes 1–2 days, it fails my primary use case. If an app is “instant” but routes through an intermediate balance, or splits one need into two cashouts with two fees, that is still a speed/fee failure even if the first notification looks fast.
How EarnIn works in practice
- Connect a bank account that receives your paycheck deposits.
- The app estimates how much of your earned wages you can access early.
- You request an instant transfer and pay the Lightning / expedited fee when you need same-day cash.
- Repayment typically pulls from your next deposit according to the app's rules.
How Grant works in practice
- Download Grant and join with the referral invite so the bonus applies.
- Connect the account they ask for and review the advance they actually offer.
- Choose same-day delivery if you need cash now and accept the fee shown before you confirm.
Pros and cons at a glance
EarnIn pros
- About $3.99 instant fee
- Simple when you are already stressed
- $35 / $35 referral
EarnIn cons
- Roughly $100 cashout ceiling
- Not enough alone for large shortfalls
Grant pros
- Signup bonus through my invite
- Stated range $25–$500
- Offer says no credit check and no late fees
Grant cons
- Delivery fee still applies for same-day
- Personal cashout log is newer than EarnIn/Tilt
Who should choose which app
Choose EarnIn if...
- People who need cash today, not in 1-2 business days.
- Anyone optimizing for fee-per-dollar on smaller advances.
- Users willing to keep a second app for amounts above ~$100.
- You specifically need: Cheapest usable instant pull when ~$100 is enough
Choose Grant if...
- People who want the invite bonus and a shot at a larger stated limit.
- You specifically need: People who want a bonus on signup and a wide stated range
Skip both (for this matchup) if...
- Your situation matches a EarnIn skip reason: Anyone who needs $250–$400 in a single advance with one tap.; People who refuse to connect payroll-linked banking data (common to this category).
- Or a Grant skip reason: Anyone who will not read the delivery fee before confirming.
- You have not checked cheaper Top 5 options first — especially EarnIn for fee efficiency and Tilt for amount/price balance.
Real scenarios: which one I would open
Scenario A — I need about $80–$100 today with minimal fee damage. I compare both on fee_num style pain. Right now that usually favors the lower fee pattern between EarnIn (~$3.99 per transfer) and Grant (Same-day delivery fee (offer-based)). I would lean EarnIn.
Scenario B — I need a larger single advance for a bill that is bigger than a tiny bridge. Amount experience matters more: EarnIn (Often capped around $100 per cashout) vs Grant (Offer range about $25–$500). I would lean Grant if the fee stays tolerable.
Scenario C — I am already stressed and hate complicated onboarding. Subscription-first and rewards-heavy flows lose. Gerald/Vola-style paywalls are automatic skips. Between EarnIn and Grant, I punish whichever adds more steps before money moves.
Scenario D — I might use cash advances every month. Recurring users should optimize a stack, not a single loyalty relationship. My default stack is still EarnIn → Tilt → Brigit → MoneyLion → Credit Genie. This EarnIn vs Grant page tells you which of the two deserves a slot if both are candidates.
Referral bonuses and support links
EarnIn referral note: Both get $35. Grant referral note: Bonus when you join via my invite. Every Sign up for … button goes through go/affiliates.js so you can update referral URLs in one place.
Referral links never change the ranking method. If an app is expensive or annoying, it still gets called expensive or annoying.
FAQ: EarnIn vs Grant
Which is better overall, EarnIn or Grant?
EarnIn ranks higher in my personal scoring. Scores: EarnIn 9.2/10, Grant 7.0/10.
Which has lower fees?
EarnIn has the better fee pattern in my notes (~$3.99 per transfer).
Which gives more cash?
Grant has been stronger on amount (Offer range about $25–$500).
Are these payday loans?
Most market as cash advances or earned wage access. Fees and subscriptions can still get expensive. Use them as short bridges, not income.
Final verdict
If I could install only one of these two tomorrow, I would choose EarnIn. That is not a brand endorsement — it is the score from living with both fee models and amount patterns month after month. Re-check live offers before you commit, because limits move. For deeper detail, read the full EarnIn review and Grant review, or return to the cash advance app comparisons hub.
Related searches this page is meant to answer: EarnIn vs Grant, Grant vs EarnIn, EarnIn or Grant for instant cash, EarnIn fees vs Grant, and which cash advance app is cheaper.
Methodology and bias notes
Every comparison on Cash Advancement Apps uses the same lens: I need cash advances on a regular monthly cadence, I prioritize instant delivery, and I care about the net result after fees, subscriptions, and transfer friction. I do not award points for celebrity ads, cartoon mascots, or “up to $500” banners I never personally received.
For EarnIn vs Grant specifically, I weighed score (9.2 vs 7.0), fee pattern, amount experience, monthly structure, and onboarding friction. If your bank deposits, state rules, or employment pattern differ, your offers can differ — treat this as a field guide, not a guarantee.
I will keep updating these pages as apps change cashout behavior (for example, split cashouts) or subscription gates. If you have a different experience, that can still be valid — underwriting is personalized — but the structural red flags (pay before estimate, near-$50 cashout fees, tiny $50 ceilings) are worth publishing clearly.
If you are building a multi-app stack, do not marry either EarnIn or Grant. Pull the cheaper efficient option first, then the better amount option, then stop before you enter predatory fee territory. That discipline matters more than winning an internet argument about which logo is “best.”